The 1% rule is a helpful guideline for calculating your baseline rent price. Multiply the purchase price of your home (plus the cost of any necessary renovations and repairs) by 1%. The result is the minimum amount you should charge tenants to stay profitable.
Ensure your rent price is appropriate for your property type, taking into account its location, condition, and amenities. Research the rates that landlords in your area are charging for properties similar to yours to ensure your price aligns with market expectations.
Stay informed about trends in the rental market and the broader economy. Be willing to adjust your price as necessary to stay competitive. When advertising your rental, always highlight its best features and perks to justify the price you’re charging.
A capital gain is the profit you earn when you sell your rental property for more than you originally paid.
A short-term capital gain occurs when you sell your rental after holding it for a year or less; it is taxable at your ordinary tax rate. Long-term capital gains apply to sales where you owned the rental for over a year; these are taxable at 0%, 15%, or 20%, depending on your taxable income.
Several strategies exist for minimizing capital gains taxes. These include using a 1031 tax-deferred exchange, applying losses from other investments against your profit, and converting your rental into a primary residence.
A capital gain on a rental property occurs when you sell it for more than you originally paid to purchase it.
In Canada, 50% of capital gains are taxable. You must add the capital gain from your rental sale to your annual income and pay tax on it at your marginal tax rate (the income tax bracket you fall under).
You can employ strategies to reduce your capital gain tax liability. These include claiming specific rental property deductions, contributing your profit to an RRSP, and offsetting it using a capital loss. It’s also wise to postpone your property’s sale to a year in which you earn a low income.
When you make a capital improvement to your rental property, you increase its value, extend its life, or adapt it to a new use.
Repairs are recurring and preventative activities that keep your rental property in working condition. They don’t enhance your property’s value.
You can’t write off a capital improvement as a regular expense; you must depreciate it over time. Repairs, on the other hand, are fully deductible expenses in the year that you made that repair.
The mortgage renewal period typically begins a few months before the mortgage term ends, so take that time to review new terms with your current lender or explore other options.
Factor in the interest rate, how long you’ll have the mortgage, and what your financial goals are.
Always get advice from a mortgage professional who can support you throughout the mortgage renewal process.
Rental property depreciation is a method that accounts for the loss in value of real estate property over time due to wear and tear. You can claim depreciation as an expense on your tax return to lower your tax liability.
The Internal Revenue Service (IRS) limits how much depreciation you can deduct against your rental income annually. Most rental properties are depreciated over 27.5 years.
You can claim depreciation on the initial purchase price of the rental property, eligible closing costs, and improvements costs. However, you can’t depreciate the land, as it doesn’t lose value over time.
Rental property depreciation is an accounting method used to deduct the loss in value of a rental over time due to everyday usage.
You can claim capital cost allowance (CCA) on depreciation as a tax deduction to reduce the amount of taxes that you owe to the Canada Revenue Agency (CRA).
The CCA that you’re allowed to claim is based on the type of rental property and the year that you bought that property.
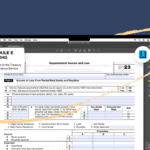
Schedule E is a tax form that reports supplemental income, including rental income and real estate investments, to the Internal Revenue Service (IRS). You must complete this form if you received income from a rental property.
Schedule E must be attached to your primary tax return (Form 1040) and submitted to the IRS by mid-April of each tax year. You can request an extension until mid-October.
Schedule E has four parts, but you only need to complete the section that applies to your tax situation.
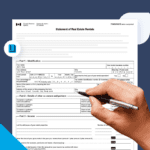
The T776 Statement of Real Estate Rentals form allows you to report your rental income and expenses for tax purposes. The Canada Revenue Agency (CRA) recommends submitting this form with your tax return.
To complete the T776 form, you must provide basic info about yourself and your rental property, list the total income earned during the year, and deduct eligible expenses.
The trickiest section of the T776 form is the calculation of capital cost allowance (CCA), a deduction you can claim to account for depreciation. If you need help determining this amount, consult with a tax expert.
Remembering to record your transactions is just one reason why tracking rental expenses can be tedious, but our template makes the task easy. Download the rental property expense sheet and follow our guide to simplify how you manage your expenses.
Some rental expenses occur regularly, like utilities payments. Others appear out of the blue, like emergency repairs. You can claim both as tax-deductible expenses.
When tracking your rental expenses, stay consistent: choose a standard naming system for files and record transactions as they show up, so you or your bookkeeper can easily interpret expenses when it comes time to file your taxes.
Should you hire a bookkeeper or accountant to manage the finances for your rental business? The answer depends mainly on what areas you need help with. Bookkeepers focus primarily on recording and processing day-to-day transactions, while accountants provide general financial advice.
Hiring a bookkeeper or accountant is a great way to save time, keep your financial records up to date, and benefit from the expertise of a qualified professional. However, it can be a costly option. You also bear responsibility for any mistakes they make, including those on your tax return.
Only hire a bookkeeper or accountant after interviewing them first. Ask about their qualifications and experience, the software they use, the types of services they offer, their billing rate, and how they keep clients’ financial details safe.
Failing to crunch your numbers properly can lead you to make poor financial decisions for your rental business. Our guide will show you how to set up an accounting system to help you avoid costly mistakes.
Getting organized is the first step in managing your rental’s accounting. Open a separate account for your rental business to collect rent from tenants and pay for expenses. Keep your personal and rental business transactions separate and store all financial documents digitally for easy retrieval.
To ensure accurate and timely accounting records, choose a method for tracking your income and expenses and stick to it. Learn the basics of accounting and taxes, but hire a professional to help you with anything you find overwhelming.